Strong green Triodos covered debut reflects its ESG mission
Triodos Bank successfully debuted in covered bonds with a €500m three year green bond on Thursday, which leveraged the Dutch issuer’s strong ESG character to achieve a strong hit rate among investors and help it overcome uncertain market conditions.
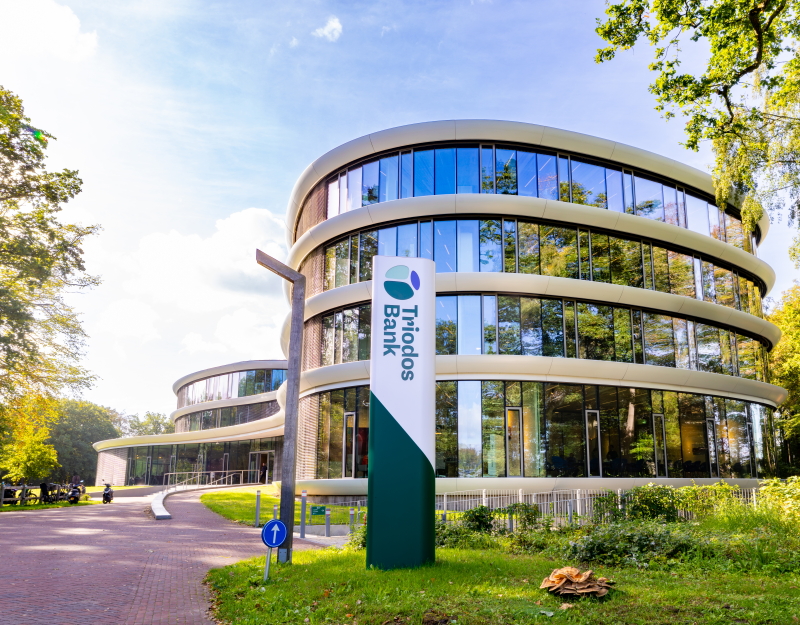 Triodos turned to covered bonds after deciding to make more use of wholesale funding, according to Arjan van Bussel, group director treasury. Triodos Bank has sold senior preferred paper, but although this provided funding, it was issued to meet the bank’s MREL requirement. The Dutch central bank (DNB) removed this requirement in April, meaning that no further senior preferred issuance is anticipated.
“When we took the decision to start diversifying our funding sources, we considered how best to do so, what instrument would be the cheapest to deliver,” said van Bussel. “And given the substantial amount of Dutch residential mortgages we have on our balance sheet, we quickly concluded that a covered bond programme was the way to go.”
Triodos had previously printed a retained RMBS transaction, but felt that a covered bond programme would prove more efficient for the more regular issuance the bank plans to pursue than one-off securitisation.
All Triodos’s previous public bond issuance – Tier 2 as well as senior preferred – has been in green format, and its covered bond issuance will maintain this record. This, according to van Bussel, is a consequence of the bank’s mission.
“We are a bank established in 1980 really with a clear focus on impact finance,” he said. “And if you focus on impact finance, then you have green assets on your book. That then facilitates the issuance of green bonds – and in this case, green covered bonds, because we have a substantial amount of residential mortgages.
“People also expect that of us.”
After having made the decision to take up covered bonds and begun preparations, around the turn of the year the bank “shifted gears”, said van Bussel, and following regulatory approval, the programme, arranged by Rabobank, was announced on 2 June.
Triodos nevertheless always planned to wait until after the summer season to approach the market, to allow it time for a non-deal roadshow, with a view to looking for opportunities after the September Seville gathering of covered bond market participants. During this period, its team – including CFO Kees Van Kalveen – met with over 80 accounts, in person and virtually, to highlight Triodos’s differences to “mainstream banks”.
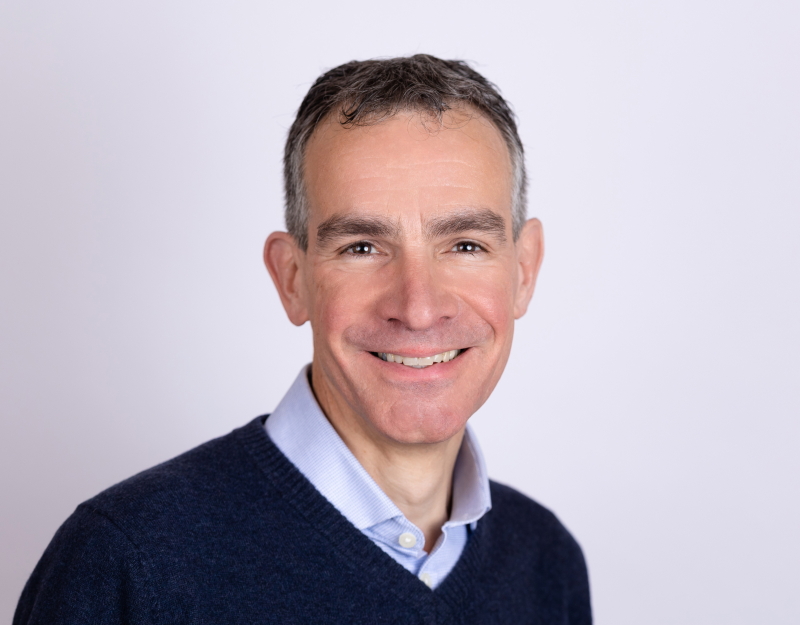 “We had intensive discussions with many, many investors in the lead-up to this,” said van Bussel (pictured), “and we of course highlighted the sustainable finance focus of the bank. We still follow the clear mission of the people who founded the bank, which is to use finance to make the transition that is necessary for climate reasons, but also to support inclusion. We are green – but not just green: we are focused on all the three letters, the E, the S, and the G.
“This also translates into our mortgage product offering. We were, for example, the first in the Netherlands to link the pricing to the EPC label of the house – we are very happy that others have followed us: if we can change the financial world so that everyone starts using the right criteria that we do, then the world will benefit from that.”
At the same time as underlining its distinctive ESG characteristics, the bank was keen to highlight the similarities its covered bonds share with those of its peers, namely that the collateral comprises Dutch prime residential mortgages, and that it is a “market standard” programme, said van Bussel.
Having concluded its planned marketing, Triodos Bank – like other debutants, including Spuerkeess and Fairstone Bank that had also seen the Spain covered bond gathering as a potential launchpad – found that market conditions had deteriorated compared to the receptive environment beforehand.
“After Seville, we started looking for the window to jump into the market, but the world had changed due to geopolitical reasons and the volatility in the financial markets of course increased,” said van Bussel.
However, a semblance of stability over the past two weeks – underlined by a €750m three year Raiffeisenlandesbank Oberoesterreich deal last Tuesday surprising to the upside – encouraged Triodos to proceed.
“We saw an opportunity and decided this would probably be the best opportunity we’d get this side of year-end,” said van Bussel. “We did, of course, consider if we should postpone to next year, but there was nobody who could really tell me whether next year would be better or worse. People noted that typically January is a good month, but the world is different now, and things that we have learned in the past, we cannot just extrapolate into the future.
“That made us conclude that, yes, there is a window out there – let’s grab it!”
Triodos’s mandate was therefore announced last Tuesday, teeing up a €500m no-grow three year for launch in the near future, subject to market conditions, via ABN Amro, Deutsche, DZ, Natixis and Rabobank.
And on Thursday morning, the leads opened books with guidance of the mid-swaps plus 35bp area for the November 2029 issue, expected rating AAA (Fitch). After around an hour and 20 minutes, they reported books above €1.5bn, including €160m of joint lead manager interest, and after around two hours and 40 minutes, the spread was set at plus 28bp on the back of books above €1.9bn, including €210m of JLM interest. The final book was above €1.8bn, including €151m of JLM interest, with 57 accounts allocated.
“We are happy,” said van Bussel. “We were careful with the IPTs, but then got so much attention that we were able to lower the spread by 7bp, which shows how strong the book was.
“And if you look at what we could have achieved two or three weeks ago, we would not have been able to get down to this level.”
The strength of the window was backed up by two other issuers successfully tapping the euro covered bond market on Thursday, Crédit Agricole Italia and ING Belgium, which made it the busiest day since September when combining the number and volume of issues.
Sjors Hoppenbrouwers, director, DCM Financial Institutions Origination, at arranger and joint bookrunner Rabobank, said the initial price guidance was arrived at after a price discovery process and reflected investors’ interest in receiving a pick-up over top tier Dutch names and also a premium for the inaugural nature of the trade.
“The green element was really helpful,” added Hoppenbrouwers, “not necessarily in terms of pricing, but as much to get investor attention.
“Triodos was already known by many investors to be a leading ESG bank, and with its green debut, Triodos has now successfully established a strong reference point in the covered bond market.”
Christian Klocke, FIG syndicate, DZ Bank, said Triodos’s marketing had clearly made a difference.
“I’m not sure I’ve ever seen such a great match between the marketing account list and feedback, and the order book,” he added. “So that’s outstanding.”
Asset managers were allocated 43%, banks 32%, central banks and official institutions 17%, hedge funds 6%, and insurance companies and pension funds 2%. Dutch accounts took 31%, the Nordics 22%, Germany 18%, Luxembourg 13%, the UK 7%, France 4%, southern Europe 3%, and others 2%.
“I’m proud that so many of the investors we visited took part in the transaction,” said van Bussel. “If you are an inaugural issuer, how do you distinguish yourself from the others that already exist? I think the answer, we have shown, is being a green issuer issuing a green covered bond.
“I asked investors how important it is that it is green,” he added, “and the real ESG accounts of course said that it is super-important. Others said that it’s a nice-to-have and that they would look at it with different eyes if it has a green label or if they think the issuer is green. So it did help us get past the door with certain investors and also in getting the tickets that investors were willing to buy.”
The arrival of a new Dutch issuer has also been welcomed by market participants as a counterweight to the loss of two others, with Knab (formerly Aegon) being merged into Austria’s Bawag, and ABN Amro acquiring NIBC.
The covered bond programme will now be Triodos’s main wholesale funding programme, said van Bussel, with regular issuance that could put it in the same bracket as existing mid-sized Dutch issuers.
Triodos photo credit: Michiel Ton