Spuerkeess puts Luxembourg on the map with quality debut
Spuerkeess’s recent debut covered bond, a €500m seven year green issue backed by domestic mortgages, aligned Luxembourg with European standards, and demand for the offering amid challenging conditions allowed the bank to achieve its goals, Spuerkeess’s Claude Origer told The CBR.
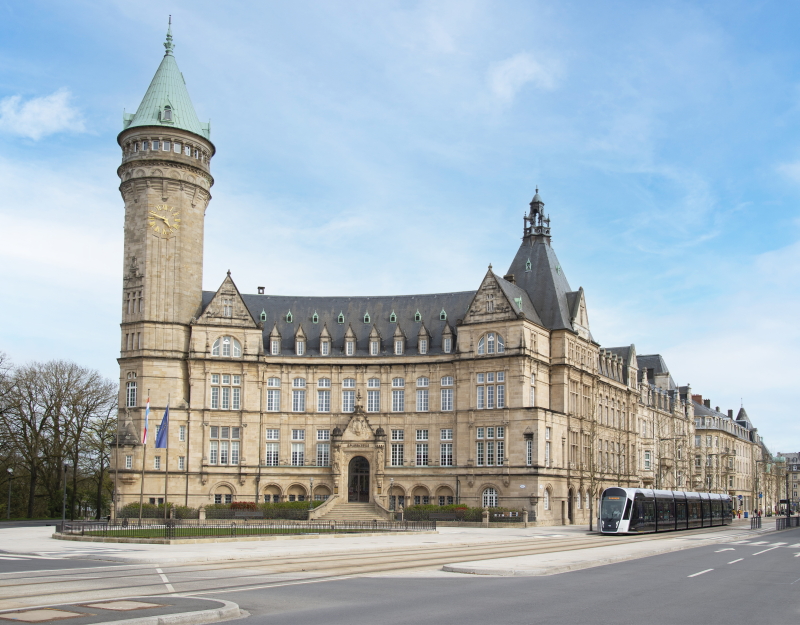 The covered bond, priced on 30 September, comes after Spuerkeess (or BCEE, Banque et Caisse d’Epargne de l’Etat, Luxembourg, in full, but known by a shortened Luxembourgish version of its name domestically since 2020) last year issued its first senior unsecured benchmarks, a €500m six year senior preferred bond in March 2025 and also a €500m six year senior non-preferred in November 2025.
“Spuerkeess is well funded by our customer deposits, with a loan-to-deposit ratio well under 70,” Claude Origer, Head of Department, Global Markets at Spuerkeess told The Covered Bond Report. “Nevertheless, the bank took a strategic decision in recent years to diversify our funding base and to add contractual long term funding.
“That was around the same time that the covered bond directive was incoming, and in light of that, it clearly made sense to look at this most liquid, cheapest, and operationally relatively straightforward instrument for long term bank funding.”
As well as being the first ever Luxembourg covered bond backed by domestic residential mortgages, Spuerkeess’s debut is the first since the country updated its legislation in 2021 in conjunction with the European Covered Bond Directive, which was key to the inaugural trade being the first from a universal bank in Luxembourg.
The updated framework allowed for the direct issuance of covered bonds by universal banks as well as specialised banks. The existing lettre de gage legislation that had previously constituted Luxembourg’s covered bond framework was based on the specialist banking principle that had been a feature of Germany’s Pfandbrief market when Luxembourg legislation was first established – although Germany itself subsequently abandoned the principle.
Previous Luxembourg covered bond issuance had been primarily driven by subsidiaries of German banks taking advantage of greater flexibility offered by the jurisdiction than the Pfandbrief market to issue primarily public sector-backed issues. The last such issuance in benchmark format was a €500m seven year issue for NordLB Luxembourg Covered Bond Bank in 2020 and it is the only previous benchmark outstanding.
The update to Luxembourg’s legislation was made very much with domestic banks in mind, with input from the Luxembourg Bankers’ Association (ABBL), of which Spuerkeess is a member.
 “For us, it was quite important, in the covered bond space, to align the law as much as possible with the European standard,” said Origer (pictured). “That’s why under the new law you can issue both premium European covered bonds and still also the old-style lettres de gage.
“Setting up a specialised bank would have been costly to us,” he added. “It was important to do it on-balance sheet, in the same way that our German neighbours now do it, that our Belgian neighbours do it.”
Luxembourg’s legislation imposes an asset encumbrance limit similar to the framework previously in place in neighbouring Belgium, where the statutory limit was abolished in 2024. In Luxembourg, the aggregate cover pools related to covered bonds issued by a universal bank may not exceed 20% of its total on-balance-sheet liabilities, including own funds and after deduction of eligible deposits.
Spuerkeess’s €7.5bn programme for the issuance of obligations garantie européennes (de qualité supérieure) was approved by the Commission de Surveillance du Secteur Financier (CSSF) in July and, with its first half results due on 21 September, Spuerkeess eyed the September industry gathering in Seville as the launchpad for its debut with pre-marketing to investors.
“Our covered bond story is really about having a triple-A instrument from a triple-A country by a AA+ bank, with only Luxembourgish mortgages,” said Origer.
Spuerkeess, which has a 52% share of the Luxembourg retail mortgage market, is rated Aa3/AA+/AA (Moody’s/S&P/Scope).
“It gives investors the opportunity to invest in something that provides them with diversification from what they are usually offered,” he added. “And then the cherry on top is the green framework.”
The covered bond is Spuerkeess’s second benchmark green bond, its first having been the €500m senior preferred deal in March last year. The use of proceeds are energy efficient buildings and the framework is aligned with the ICMA Green Bond Principles.
The bank also highlighted the update to Luxembourg’s covered bond legislation in its meetings with investors.
 “A lot of accounts were familiar with lettres de gage and their rather idiosyncratic history,” said Julien Kohn, Investor Relations Manager at Spuerkeess (pictured), “so we did a lot of work explaining the new framework and its alignment with European standards.”
Although market conditions post-Seville had deteriorated from those that had seen a month long boom in issuance from mid-August, Spuerkeess took advantage of a relatively stable market on 30 September to enter the market – issuing what was ultimately the only euro benchmark covered bond of the week, and one of only two euro FIG benchmarks that week.
Leads Belfius (global coordinator), Deutsche, LBBW and Natixis went out with guidance of the mid-swaps plus 38bp area for the €500m no-grow October 2033 green covered bond, expected rating Aaa. After around two hours, the leads reported books above €1.5bn, including €75m of joint lead manager interest, and after a little over three hours, the spread was set at 31bp on the back of orders above €1.8bn, including the €75m of JLM interest, and the final book was reported at that level.
“We are very happy the first transaction went so well,” said Origer. “Not only the oversubscription, but also the quality of the order book was quite impressive, including some official institutions and central banks, which is not always the case for covered bond issuance.
“The spread may have been a little wider than it could potentially have been three weeks earlier, but in the end we managed to tighten by 7bp, which is a little higher than what you usually see for covered bonds. So the result was clearly in line with what we had aimed for, even if market conditions were more difficult than previously.”
The new issue has since tightened a little to trade slightly inside 30bp, which Origer said showed the debut had struck the right balance between issuer and investor considerations.
Banks and private banks were allocated 60%, asset managers 16%, central banks and official institutions 15%, and insurance companies and pension funds 9%. Benelux investors took 36% of the paper, Germany, Austria and Switzerland 27%, the Nordics 16%, France 11%, southern Europe 5%, and the UK and Ireland 5%.
Spuerkeess plans to issue at least one euro benchmark bond a year in either a senior unsecured or covered bond format.
“The bank intends to show this regularity more through covered bonds,” said Origer, “with at least one benchmark issuance every 12 to 18 months. That will depend on market conditions, and we probably will not need to issue more than twice per year given our balance sheet of around €60bn.
“But the clear intention is to become a regular issuer.”
The inaugural Luxembourg covered bond also paves the way for other domestic banks.
“The success of our first transaction shows our peers that issuance is feasible,” said Kohn, “and we are very proud that we may have opened the market for others.”